Holding cryptocurrency, decentralized finance (DeFi) yields, and tokenized assets within a Self-Managed Superannuation Fund (SMSF) has evolved from a niche investment strategy into a recognized asset allocation framework for high-net-worth investors across Melbourne.
The rationale is clear: investing through an Australian complying SMSF allows trustees to build a diversified portfolio of digital assets within an attractive institutional tax environment.
However, operating a crypto-enabled SMSF is strictly governed by the Superannuation Industry (Supervision) Act 1993 (SIS Act), the Superannuation Industry (Supervision) Regulations 1994 (SISR), and the Income Tax Assessment Act 1997.
The Australian Taxation Office (ATO) actively monitors digital asset funds. The revenue authority uses automated data-matching programs with major Australian and international digital currency exchanges to detect unreported capital gains, off-chain asset mixing, and structural super breaches.
Engaging a specialized crypto SMSF accountant and experienced business tax accountant in Melbourne ensures your digital asset portfolio remains fully compliant with superannuation law, correctly accounted for across on-chain transactions, and optimized for maximum statutory tax efficiency.
Every SMSF holding cryptocurrency must operate within strict statutory boundaries to maintain its complying tax status:
| Statutory Provision | Mandatory Operational Requirements |
|---|---|
| 1. The Sole Purpose Test (Section 62 SIS Act) | The SMSF must be maintained for the EXCLUSIVE purpose of providing retirement benefits to members. Zero personal use allowed. |
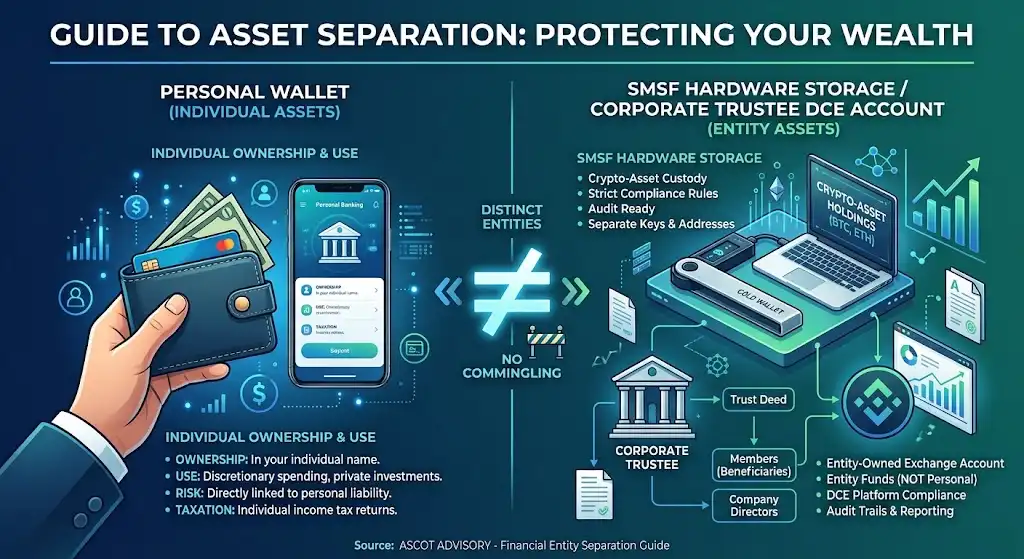
| 2. Separation of Assets (Regulation 4.09A) | Crypto assets must be completely segregated from personal holdings. Wallets & accounts must be in the Corporate Trustee’s name. |
| 3. In-House Asset Rules (Section 66 SIS Act) | Strict ban on acquiring crypto from fund members or related parties. Off-market transfers of personal crypto are illegal. |
| 4. Investment Strategy (Regulation 4.09) | Written strategy must document liquidity, price volatility, custody risk, and target asset allocation percentages. |
The fund must be maintained solely to provide retirement benefits to members (or death benefits to beneficiaries). Personal benefits—such as using fund crypto to purchase personal items, staking SMSF assets through personal wallets, or accessing liquidity for personal business ventures—constitute severe breaches of Section 62, carrying civil and criminal penalties.
Under SIS Regulation 4.09A, fund assets must be strictly separated from personal assets.
Under Section 66 of the SIS Act, an SMSF is strictly prohibited from intentionally acquiring assets from a related party (including fund members, trustees, and their relatives).
While exceptions exist for listed shares and business real property, cryptocurrency does not qualify for any statutory exception. Transferring personally owned Bitcoin, Ethereum, or other digital tokens into your SMSF is illegal. All digital assets must be purchased directly on the open market using liquid SMSF cash.
The tax treatment of digital assets within an SMSF depends heavily on transaction classifications and the fund’s operational phase:
| SMSF Phase & Transaction Type | Statutory Tax Treatment |
|---|---|
Accumulation Phase (Building Retirement Wealth) | • Realized gains (<12 months): 15.0% Tax • Realized gains (>12 months): 10.0% Tax (Reflects statutory 1/3 CGT Discount) |
Retirement / Pension Phase (Supporting Account-Based Pension) | • Realized capital gains: 0.0% Tax • Staking & Ordinary Income: 0.0% Tax (Up to Transfer Balance Cap limits) |
| Staking Rewards & Airdrops | Treated as Ordinary Assessable Income at the standard fund tax rate (15% or 0%) |
Every disposal of a digital asset—including trading Bitcoin for Ethereum, swapping tokens on a decentralized exchange (DEX), or converting crypto back to Australian Dollars—is a taxable Capital Gains Tax (CGT) event under Australian tax law.
In the accumulation phase, capital gains on assets held for longer than 12 months qualify for a one-third CGT discount, reducing the effective tax rate from 15% to 10%.
In the pension phase, all realized capital gains and investment yields supporting an account-based pension are taxed at 0% (subject to the member’s Transfer Balance Cap limits).
Our Melbourne crypto SMSF accounting practice provides end-to-end administration for digital asset portfolios:
Modern digital asset strategies often extend beyond simple buy-and-hold investments: