If you are a director of an Australian company and have received a formal Director Penalty Notice (DPN) at your Melbourne business or residential address, you are facing a strict statutory deadline. Under Division 269-25 of Schedule 1 to the Taxation Administration Act 1953, the Australian Taxation Office grants company directors exactly 21 calendar days to take specific statutory actions to avoid personal liability for their company’s unpaid PAYG Withholding, GST, and Superannuation Guarantee Charge debts.
The critical trap that catches many Victorian directors is misunderstanding when the statutory clock starts. The 21-day timeline begins on the date printed on the ATO notice, NOT the day it is opened, collected from the post office, or handed to a business tax accountant.
If the 21st day falls on a weekend or public holiday in Victoria, the deadline does not automatically extend under standard administrative frameworks; the required statutory appointments must be completed and lodged with the Australian Securities and Investments Commission (ASIC) before the countdown expires.
Resolving a 21-Day DPN requires immediate, coordinated action across legal, accounting, and insolvency disciplines:
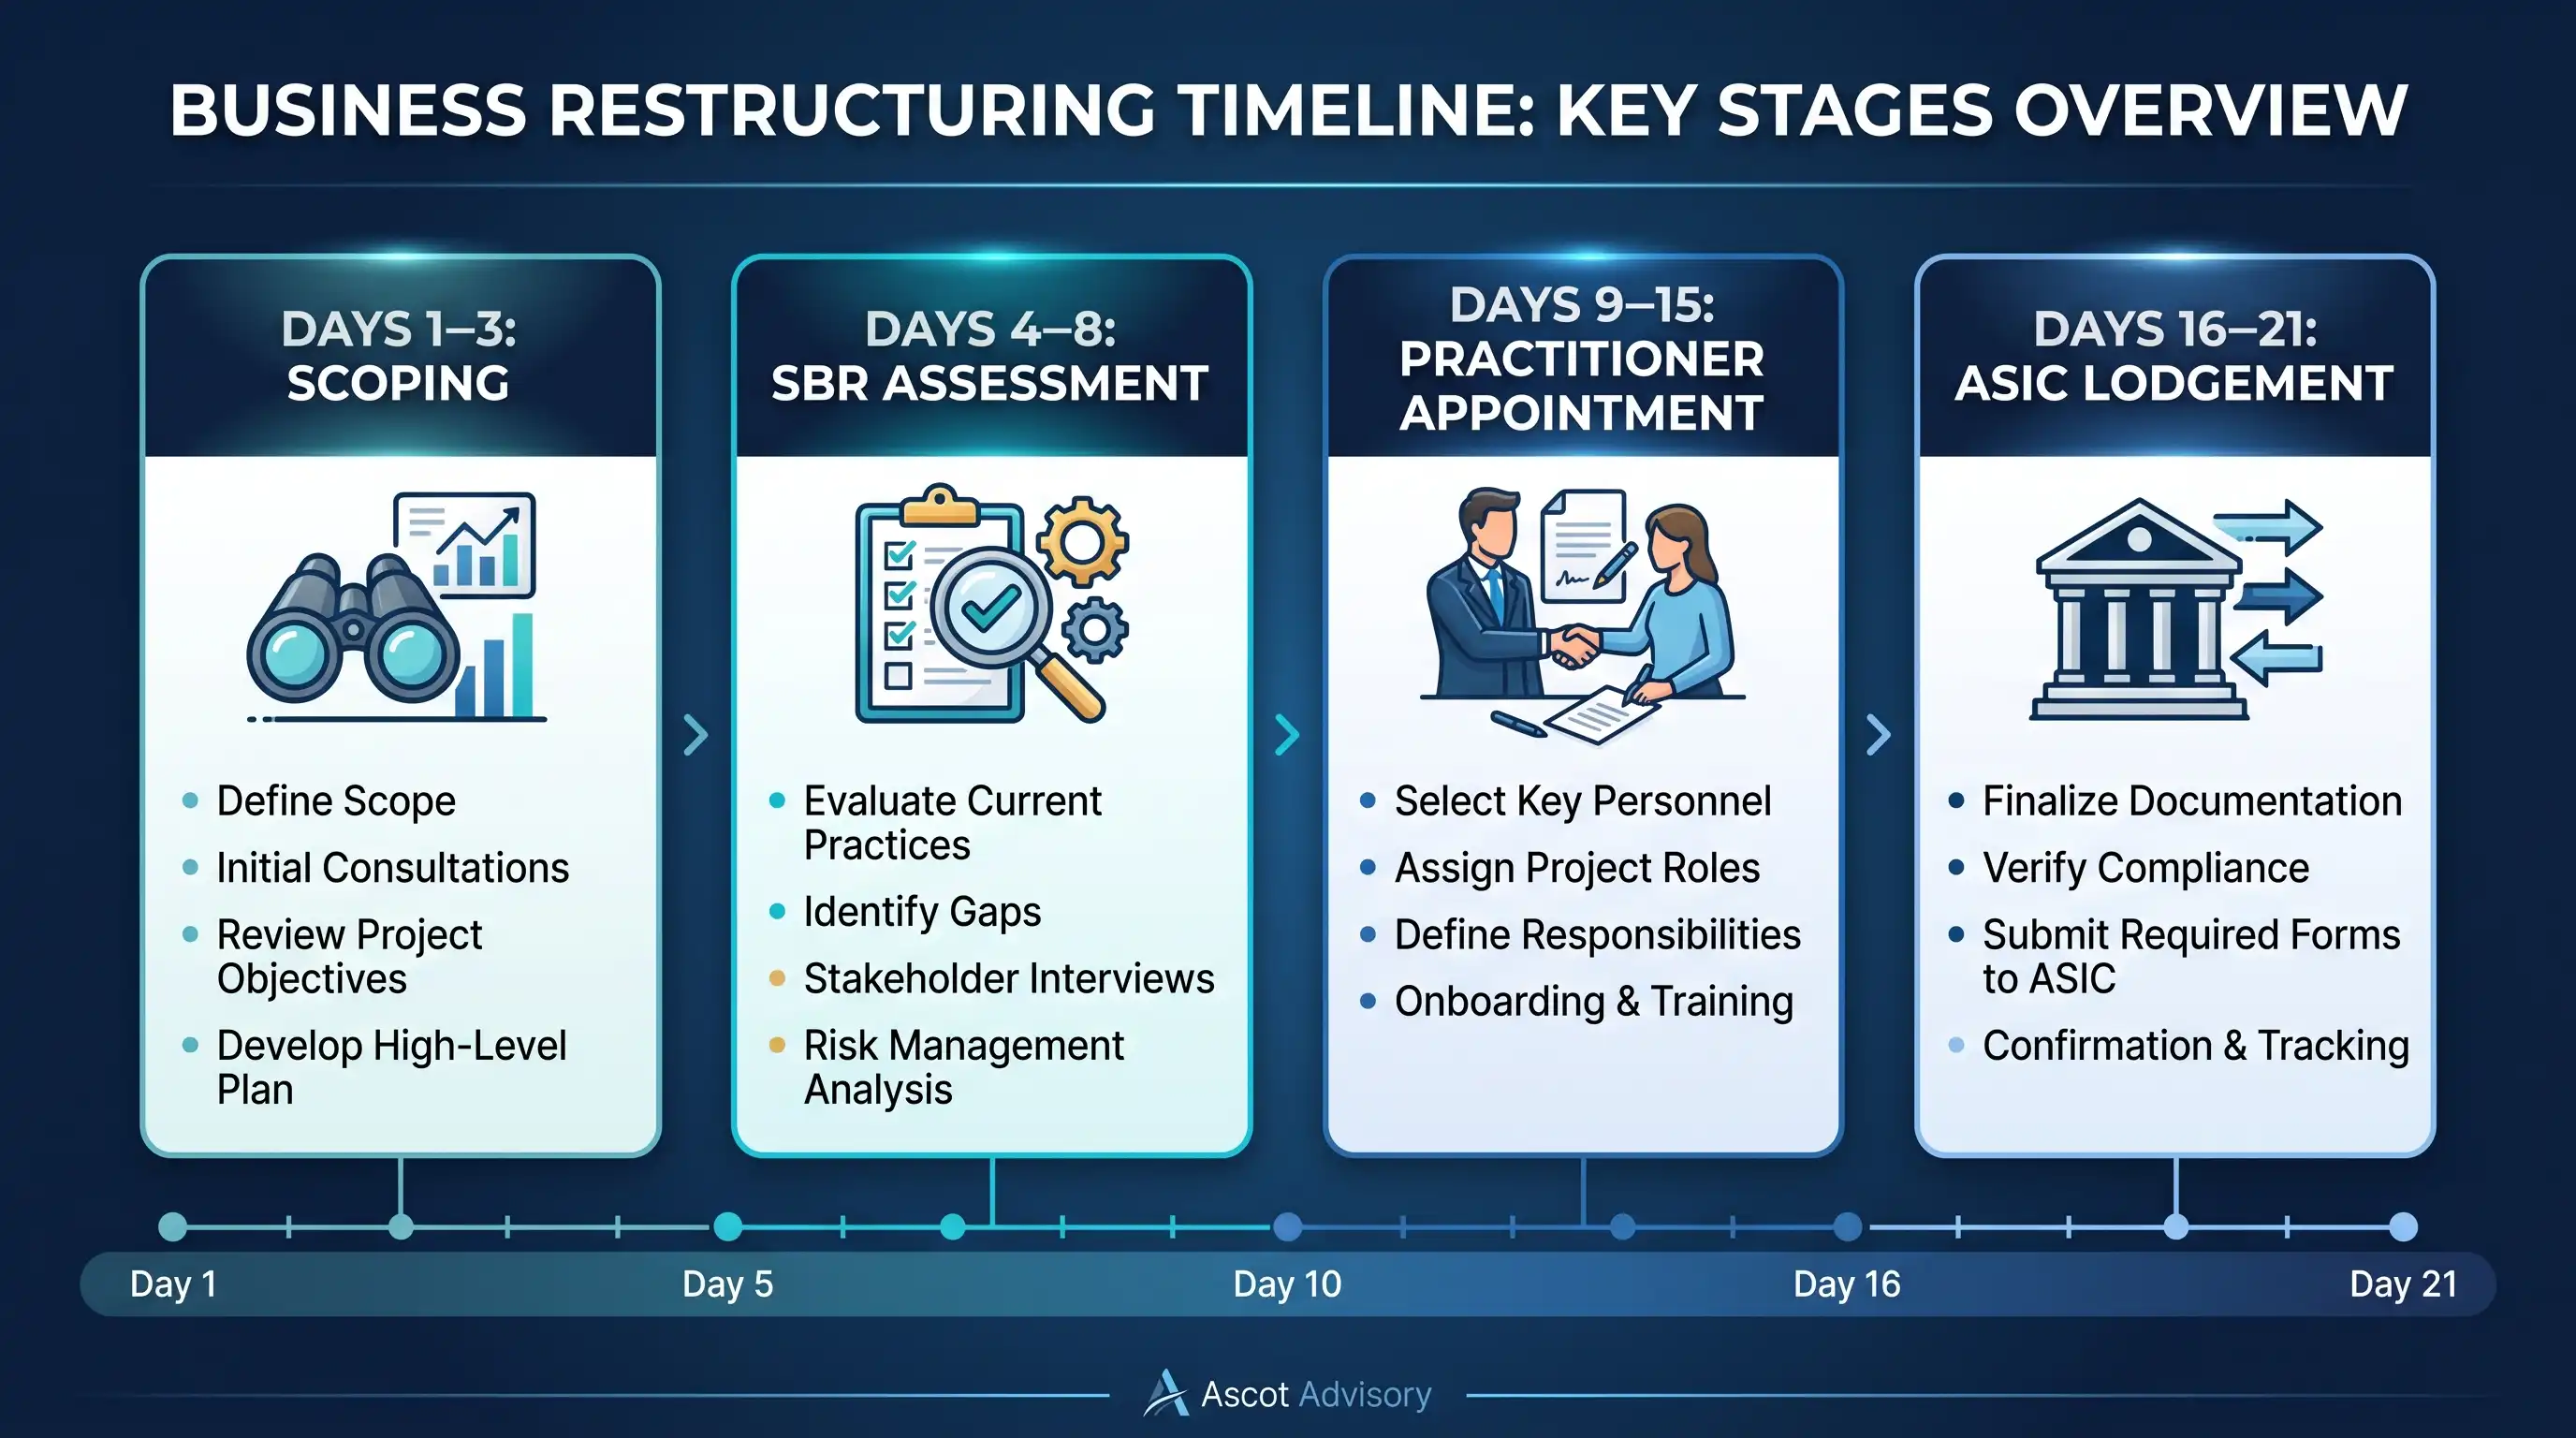
| Timeline | Operational Mandate | Strategic Focus |
|---|---|---|
| Days 1 – 3 | Immediate Liability Scoping | Distinguish Lockdown vs. Non-Lockdown liabilities. Check ASIC registered address. |
| Days 4 – 8 | SBR Eligibility Assessment | Review <$1M debt cap and confirm employee entitlements & super are up to date. |
| Days 9 – 15 | Practitioner Engagement | Formally appoint a Small Business Restructuring Practitioner or Liquidator. |
| Days 16 – 21 | Formal Lodgement with ASIC | Ensure ASIC notification is completed before 11:59 PM on Day 21. |
Our tax dispute specialists immediately review the notice details against historical ATO portal records:
For viable Melbourne businesses, the Small Business Restructuring (SBR) process under Part 5.3B of the Corporations Act 2001 is often the most effective option:
If SBR is viable, or if the company must enter Voluntary Administration (VA) or Creditors’ Voluntary Liquidation (CVL):
We confirm that ASIC has formally registered the Form 505 (Notification of Appointment) and provide written proof of the appointment to the ATO case officer handling the file before the close of business on Day 21, ensuring the statutory penalty is remitted.
| Traditional Liquidation / VA | Small Business Restructuring (Part 5.3B) |
|---|---|
| Directors lose control | Directors retain full daily control |
| Business usually ceases | Business continues normal trading |
| Severe reputational damage | Confidential restructuring process |
| High cost and fees | Lower, capped statutory fee structure |
| 100% personal DPN risk if late | Extinguishes Non-Lockdown DPN liability |
For eligible Melbourne companies, an SBR allows directors to propose a binding compromise with creditors (including the ATO). SBR plans routinely achieve debt compromises where the ATO accepts 15 to 30 cents on the dollar, payable over terms of up to 36 months without ongoing interest charges.
Most importantly, completing the appointment of an SBR practitioner within the 21-day DPN window permanently eliminates the director’s personal liability for all non-lockdown amounts listed on the notice.
If a DPN has arrived at your address:
Our Melbourne-focused tax advisory practice at Ascot Advisory provides emergency 24-hour turnaround reviews for 21-Day Director Penalty Notices. Contact us immediately to protect your personal assets before the 21-day deadline closes.