The Australian Taxation Office (ATO) has transitioned from manual, retrospective audits to an automated, data-driven compliance model. Driven by multi-billion-dollar investments in the Smarter Data program, Single Touch Payroll (STP Phase 2), secure application programming interfaces (APIs) with major banking institutions, and property title integrations with the Victorian State Revenue Office (SRO), the ATO operates an advanced risk-profiling engine.
For mid-market enterprises, high-net-worth individuals, and family offices across Melbourne, receiving an ATO “Notification of Risk Review” or “Formal Audit Notice” requires a structured, strategic response.
Audits rarely occur at random. They are triggered when an entity’s declared tax positions diverge from statistical benchmarks, when automated systems detect unaligned trust distributions, or when data-matching algorithms uncover unexplained lifestyle assets, offshore transfers, or fluctuating gross margins.
Navigating an ATO audit without specialized representation exposes taxpayers to aggressive default assessments, maximum administrative penalties (up to 75% for intentional disregard), and compounding General Interest Charges (GIC). Working alongside an experienced business tax accountant and audit representation team protects your statutory rights, controls information flow, and manages technical disputes with the revenue authority.
ATO audit activity in Victoria is concentrated across four primary tax areas:
| Audit Trigger / Area | Primary Technical Scrutiny Vectors |
|---|---|
| Division 7A Deemed Dividends | Shareholder loan accounts, missing s109N agreements, private asset use |
| Section 100A Trust Reviews | Distributions to adult children or bucket companies where benefit is retained |
| Property Development & CGT | Revenue vs. Capital account treatment of land subdivisions |
| GST, BAS & POS Integrity | Merchant banking reconciliations, undeclared cash, input tax credits |
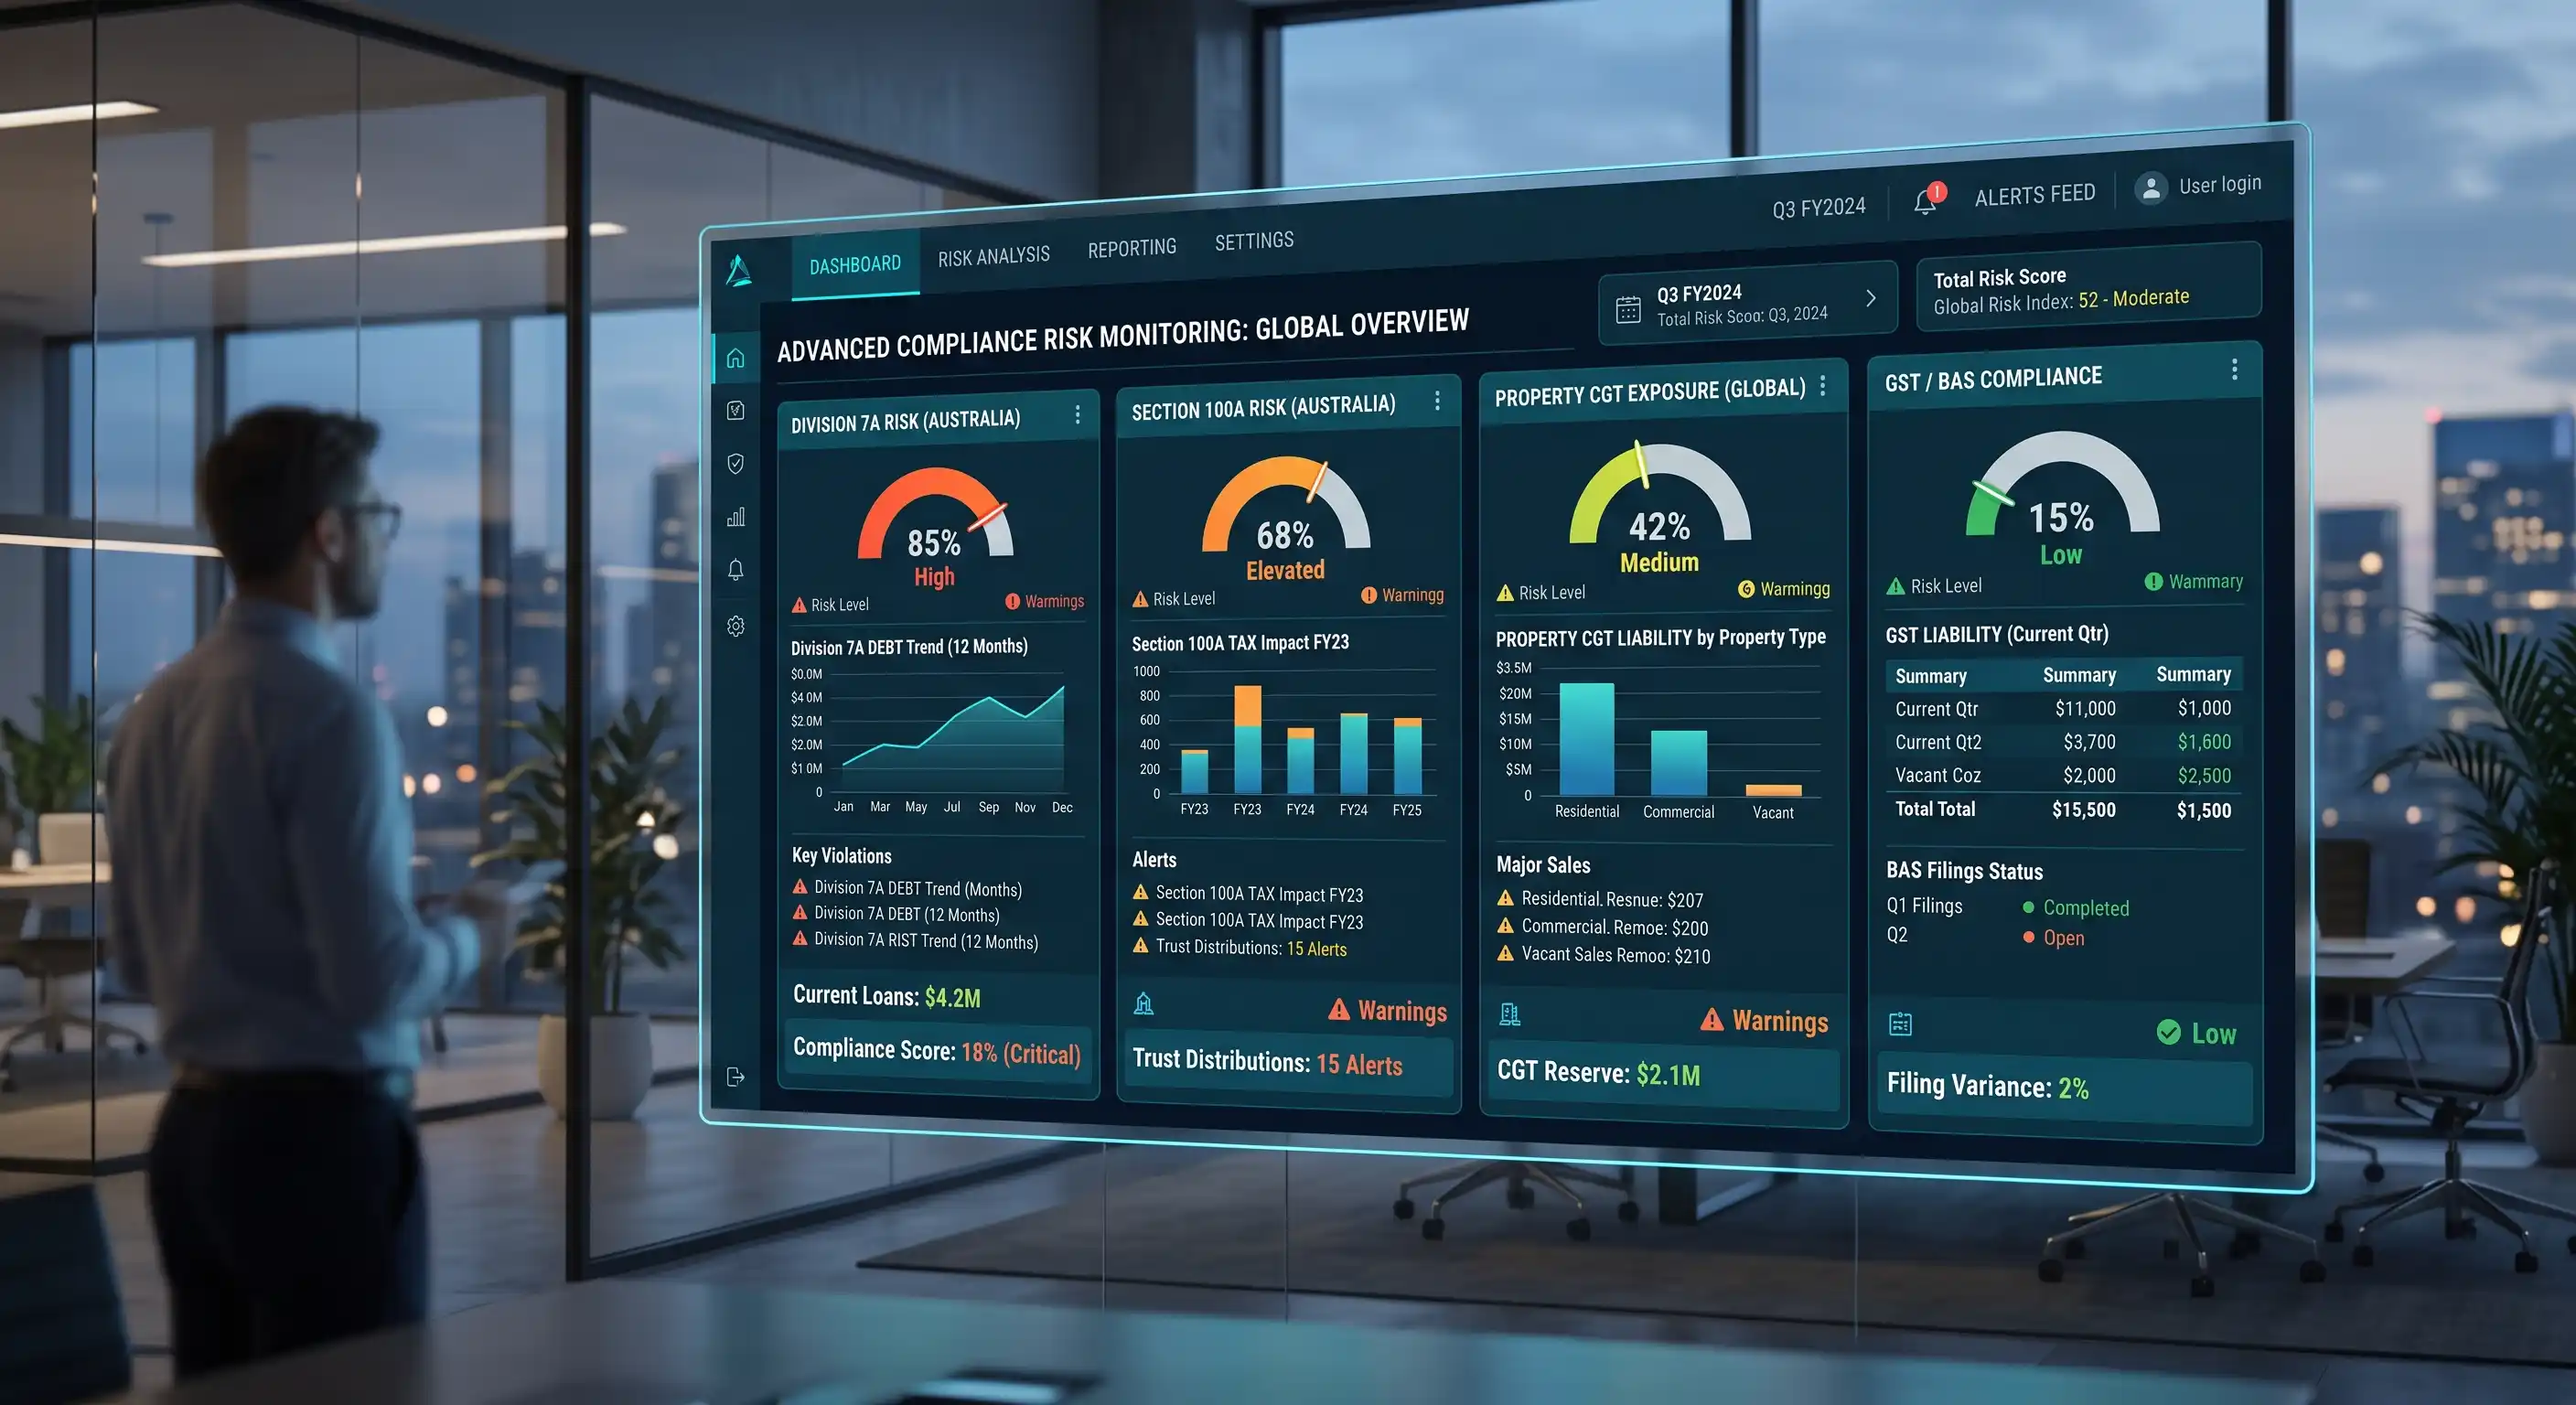
The ATO heavily scrutinizes transactions where private company funds are used by shareholders or associates. Common audit triggers include:
Under Taxation Ruling TR 2022/4 and Practical Compliance Guideline PCG 2022/2, the ATO actively challenges discretionary family trust distributions. Allocating trust income to adult children attending university or elderly parents with lower marginal tax rates—while the physical cash is retained by the family trust or transferred back to high-earning parents—is classified in the ATO’s high-risk “Red Zone”.
If Section 100A applies, the distribution is invalidated for tax purposes, and the trustee is assessed at the top marginal rate of 45% plus Medicare levy, with no statutory time limit restricting the ATO from amending historical tax years.
In Melbourne’s active property market, the ATO audits property subdivisions, multi-unit developments, and commercial conversions. The revenue authority assesses whether activities constitute the mere realization of a capital asset (eligible for the 50% CGT discount under Division 115) or an isolated profit-making scheme carrying ordinary income treatment under Section 6-5, subject to full income tax and mandatory GST under the margin scheme.
A successful audit defence follows a structured technical process designed to protect the taxpayer and limit liability:
The financial outcome of an audit is heavily influenced by administrative penalty classifications under Division 284 of Schedule 1 to the TAA 1953:
| ATO Penalty Classification | Base Administrative Penalty |
|---|---|
| Failure to take Reasonable Care | 25% of the tax shortfall |
| Recklessness | 50% of the tax shortfall |
| Intentional Disregard of the Law | 75% of the tax shortfall |
Note: Base penalties are automatically increased by 20% if the taxpayer hinders the ATO during an audit or has a prior history of tax non-compliance.
Our audit representation team builds a complete evidentiary record demonstrating that the taxpayer exercised reasonable care by relying on professional advice, maintaining contemporaneous records, and acting in good faith. By establishing reasonable care, we consistently secure full remissions of administrative penalties and negotiate significant reductions in compounding General Interest Charges.
Engaging experienced audit representation levels the playing field when dealing with the ATO. Contact Ascot Advisory to protect your assets and preserve corporate reputations.